
Phidias risk calculator
Size every trade on the Phidias Fundamental $100K from its real capital: the $3,000 max drawdown, not the $100K account. See how many losing trades end the day and the account, then run your plan 10,000 times under Phidias' own rules.
Your three numbers
- stop after 2 losses
- stop at −$200
Today
Phidias Express to Live $100KBefore each trade
Phidias Express to Live $100KYour real capital is $800, not $100,000: no daily loss limit is stated, 20 end the account. Size every trade so a normal losing streak cannot reach that limit, and set a daily limit of your own.
The loss side
your edge: +0.13R · $5 a trade on averageThe firm states no daily limit: yours is the only one.
From the starting balance, on a static floor.
Over a typical run of 323 trades at a 55% loss rate, a losing streak of 8 or more happens in 71% of runs and one of 12 or more in 10%. The account ends at 20 losses in a row.
| Losses in a row | All lose next | In a day | In 100 trades | In a typical run |
|---|---|---|---|---|
| 2 · Your stopends the day by your choice | 30% | 44% | 100% | 100% |
| 20 · Max drawdownthe account is lost | 1 in 155,864 | — | 1 in 4,213 | 1 in 1,135 |
“All lose next” is the chance that the coming trades are all losers. The other three columns are the chance that such a streak happens at least once: in a day of 3 trades, in 100 trades, and in a typical run of 323 trades (the simulation's median), the streak that ends accounts. All are exact, from your win rate.
The gain side
1 phase · $60 a winNet of losses it takes more trades: the simulation counts them.
Trade by trade at your win rate, under the firm's rules and your limits.
| Winning trades in a row | Chance in a row | What it means |
|---|---|---|
| 59 wins of $60 | under 1 in a billion | the first target in one go: the one-day rush |
| 30 wins of $60 | under 1 in a billion | half of the first target in one go |
Consistency
10,000 simulated challenges with your numbers
same seed every timeAssumes a fixed stop (−$40) and target (+$60), independent trades at a 45% win rate, the same size every trade, $0 of costs a trade, no slippage; Phidias' rules as published, checked Sep 30, 2026.
What this does not model
Variable R (stops and targets that move) · partial exits · news gaps · slippage · correlated trades · the firm's discretion · taxes.
The same strategy copied onto several accounts shares one outcome: they pass or fail together, so the odds above do not improve. Trading opposite sides across accounts to push one through (“hedged passing”) is prohibited by the firms that state a rule on it, and this planner never suggests it.
These figures treat each account as its own attempt, the best case, with the chance of one attempt from the simulation above. Each account is bought once: resets are not counted.
Left out of this run: the time limit (not published: no deadline is applied). Other rules (news trading, time limits, a minimum profit for a day to count, scaling) are not simulated: read the firm's own page.
After you pass
Express to Live Cash accountFunded from a fresh start, with your numbers: 10,000 runs trade until the first payout can be asked for, the account is lost, or 120 days pass.
- Passday 110
- First payoutday 112
- Second payouton demand
No minimum payout, buffer or target is published for this stage: a payout can be asked for as soon as the account is in profit.
What this stage publishes
- Profit split
- 80%
- Payouts
- on demand
- Payout cap
- $3,000 per bonus payout
- Consistency
- None
- Funded account
- no daily loss limit
- Reset (funded)
- None: a new account is bought
Not published by the firm, so left out of this run: the minimum payout. A day here is a trading day, counted as one day of the firm's own day rules.
Cost to get funded
price, resets, fee after passing36.2 attempts on average: $318 for the first, $318 for each of the others, plus $149 after passing
Nine times in ten one of these 83 attempts passes: $318 for the first, then $318 each time, plus $149 after passing
The firm sells no reset: each new attempt is a new account at the full price, $318.
Ways to size, compared
your plan 10,000 runs · the others 5,000 each| Way to size | Reached | Account lost | Daily limit hit | Median days |
|---|---|---|---|---|
| Same size every tradeyour plan as set | 2.8% | 3.1% | 0.0% | 110 |
| Half size near the floorwhen less than a third of the drawdown is left | 3.0% | 1.8% | 0.0% | 109 |
| Half size after 2 lossesback to full size after a win | 0.9% | 1.9% | 0.0% | 107 |
| Build a buffer firsthalf size until up half the drawdown | 0.8% | 0.1% | 0.0% | 114 |
The same trades, sized four ways. Half size when the floor gets close is the most common advice: it trades a little speed for fewer lost accounts. The best figure of each column is in accent.
If you risked…
your row 10,000 runs · the others 2,000 each| Risk a trade | Reached | Account lost | Median days | Cost to get funded |
|---|---|---|---|---|
| 1% of the drawdown$8 a trade | 0.0% | 0.0% | — | — |
| 2.5% of the drawdown$20 a trade | 0.0% | 0.1% | — | — |
| 5% of the drawdownyour plan$40 a trade | 2.8% | 3.1% | 110 | $11,671 |
| 7.5% of the drawdown$60 a trade | 27.7% | 9.7% | 96 | $1,299 |
| 10% of the drawdown$80 a trade | 49.7% | 18.9% | 82 | $789 |
The same win rate, reward, stops and rules at other sizes of risk: only the risk changes. Your own row is the simulation above; the best figure of each column is in accent.
The drawdown floor
staticRushing against your plan
the same win rate and reward| Measure | Your plan | Rushing |
|---|---|---|
| Risk per trade | 5.0% of the drawdown · $40 | 100% of the drawdown · $800 |
| Your limits | on | none |
| Reached | 2.8% | 25.8% |
| Daily limit hit | 0.0% | 0.0% |
| Account lost | 3.1% | 74.2% |
| Expected cost to get funded | $11,671 · about 1 pass in 36 accounts | $1,383 · about 1 pass in 4 accounts |
Rushing sizes each trade so an average day makes the first target in one session ($3,500 in 3 trades, capped here at your whole drawdown: one loss ends the account). Same win rate, same reward: only the size and the limits change.
Kelly and the risk of ruin
what the formulas sayKelly = win rate − loss rate ÷ reward = 0.45 − 0.55 ÷ 1.5 = 8.3% a trade, applied here to your real capital, the $800 drawdown. Full Kelly grows fastest with deep swings on the way; most traders use a quarter to a half of it. You are at 0.6 Kelly: above half, losing runs get long.
The chance a losing run eats the whole drawdown (20 losses of room) if you traded these numbers without end, on one account.
The real figure for this account: its daily limit and its targets included.
Risk of ruin ≈ e^(−r × U), where U is the losses of room (the drawdown ÷ the risk of one trade) and r solves p · e^(−r × reward) + q · e^(r) = 1 (p the win rate, q the loss rate). Kelly and ruin assume trades of the same size, one after another.
My plan
keep it beside your chart, share it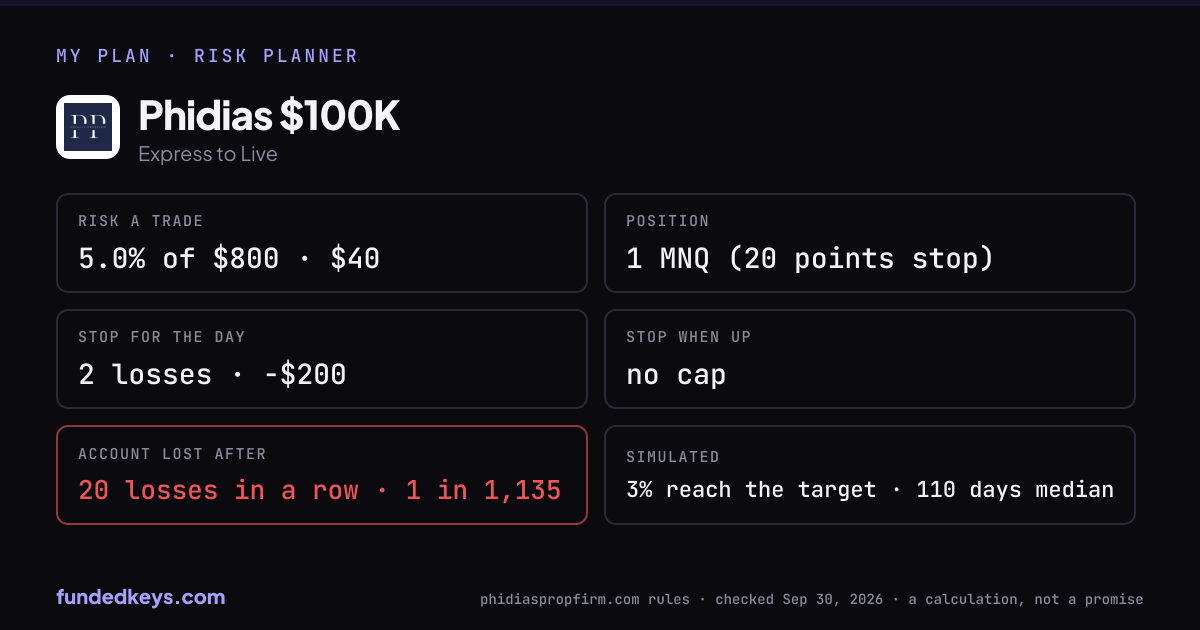
MY PLAN · Phidias Express to Live $100K
Risk per trade: 5.0% of the $800 drawdown ($40) · reward 1.5R · win rate 45% (my estimate)
Position: 1 MNQ (20 points stop)
Stop for the day: after 2 losses in a row or at −$200
Stop for the day when up: no cap
The firm states no daily limit and ends the account after 20 losses in a row (1 in 1,135 over a typical run)
Simulated with these numbers: 3% reach the target, median 110 days
Rules from phidiaspropfirm.com, checked Sep 30, 2026 · fundedkeys.com/tools/risk-planner
The card is this plan's share image: posted in Discord, Telegram or X, the link opens this exact plan.
Each run trades your numbers under the account's rules: its daily loss limit, its max drawdown (static, trailing, end of day or locking at the starting balance as the firm states it), its targets, its minimum days and its consistency rule, and under your own limits. A rule the firm does not publish is left out and named. Rules of the accounts are data of Oct 5, 2026. A calculation, not a promise. Check your own days in the consistency calculator
Phidias risk questions, answered from its rules
How much should I risk per trade on Phidias' $100K account?
Risk a share of the $3,000 max drawdown, not of the $100K: that $3,000 is what the Phidias Fundamental $100K can lose before it ends, so it is your real capital. At 5% of it a trade risks $150 (0.15% of the account); 2.5% is $75 and 10% is $300. With a 45% win rate and rewards of 1.5R, 59% of 10,000 simulated runs reach the target and 14% lose the account. A calculation, not a promise.
How many losing trades in a row end the day or the account on Phidias' $100K account?
Phidias states no daily loss limit on this account, so only the max drawdown ends it: at 5% of the drawdown a trade ($150), 20 losses in a row reach the $3,000 max drawdown. End of day: the floor rises with your best closing balance, so after a run of winning days it takes fewer. Over a typical run of 242 trades at a 55% loss rate, a losing streak of 8 or more happens in 60% of runs and one of 11 or more in 14%; a streak of 20 has a 1 in 1,545 chance of happening in such a run.
Does Phidias have a time limit or a consistency rule on the $100K account?
Phidias states no time limit for the Phidias Fundamental $100K. There is no consistency rule. At least 3 trading days are required.
What does Phidias' $100K account cost to get funded, with retries?
The Phidias Fundamental $100K costs $273 (list price). A fee of $149 is paid once, after passing. At the opening plan (5% of the drawdown a trade, 45% wins, 1.5R), 59% of attempts reach the target: 1.7 accounts bought per pass. Counting each retry at $64 (retries at the $64 reset), the expected cost is $466, and $550 covers 3 attempts, enough to be funded nine times in ten. It is a monthly plan: it bills again each month, and these figures count the first month only.
Rules and sources: Phidias review · Risk planner for every firm · consistency calculator · methodology